Introduction
If you've been comparing credit cards lately, an Axis Bank credit card has almost certainly come up in your research. As the fourth-largest credit card issuer in India, Axis runs a genuinely wide lineup, everything from a completely fee-free Neo card to the invite-only Reserve at the very top. But here's what trips up a lot of firsttime applicants: with over a dozen active variants and fee structures that range from nil to five figures, picking the wrong one can mean paying for perks you'll rarely touch. This guide breaks down the major card categories, what they genuinely cost, and how to pick one that actually fits your spending pattern rather than the flashiest welcome offer.
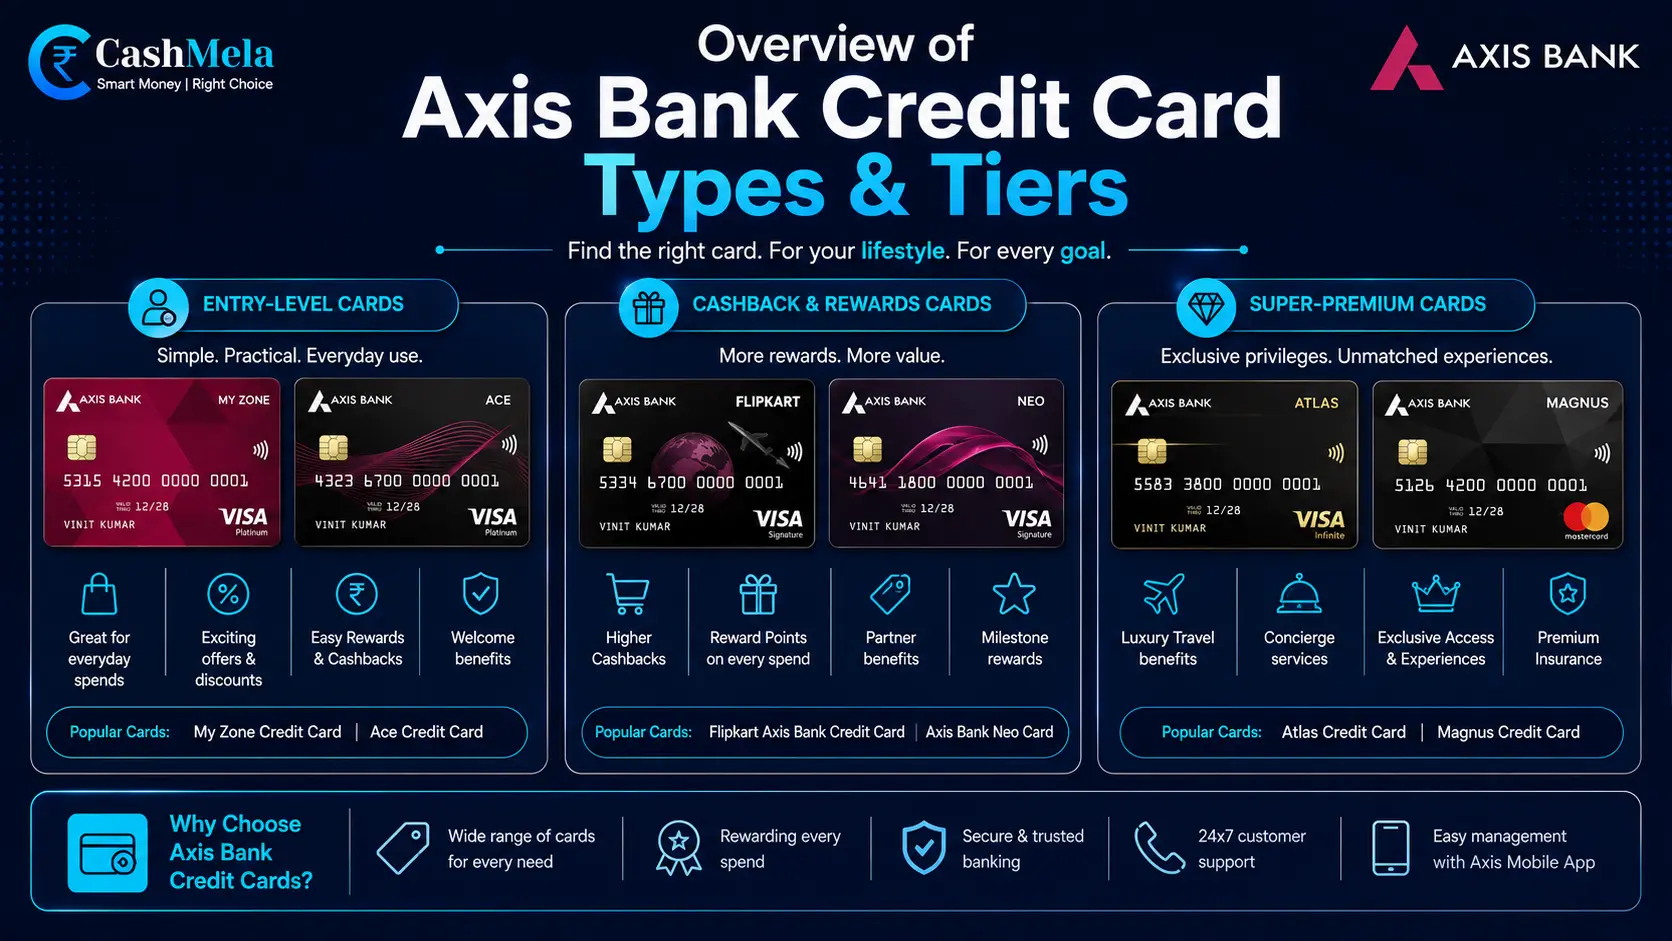
The Main Axis Bank Credit Card Categories Worth Knowing About
Let's clear up the confusion first, since this is where most applicants get stuck. Axis groups its cards loosely by spending style and income tier, and understanding this makes the decision considerably easier.
Card Categories at a Glance
- Lifetime-free cards like Neo RuPay: Built for UPI-heavy spenders with genuinely zero annual fee
- Flat-rate cashback cards like ACE: Returning 2% on most spends and 5% on select bill payments
- Co-branded cards like Flipkart Axis and Samsung Axis: Offering category-specific perks for platform loyalists
- Premium and super-premium cards like Magnus: Carrying steep fees but genuinely rich travel and lounge benefits
Take Arjun's story as an example. A software engineer in Hyderabad, he initially applied for the premium Magnus card after seeing its welcome voucher advertised everywhere. Six months in, he realized he was paying a hefty annual fee for lounge visits he used maybe twice. Switching to the ACE Axis Bank credit card instead meant a far lower fee and flat cashback that actually matched his everyday spending on bills and groceries.
Popular Axis Bank Credit Card Tiers Compared
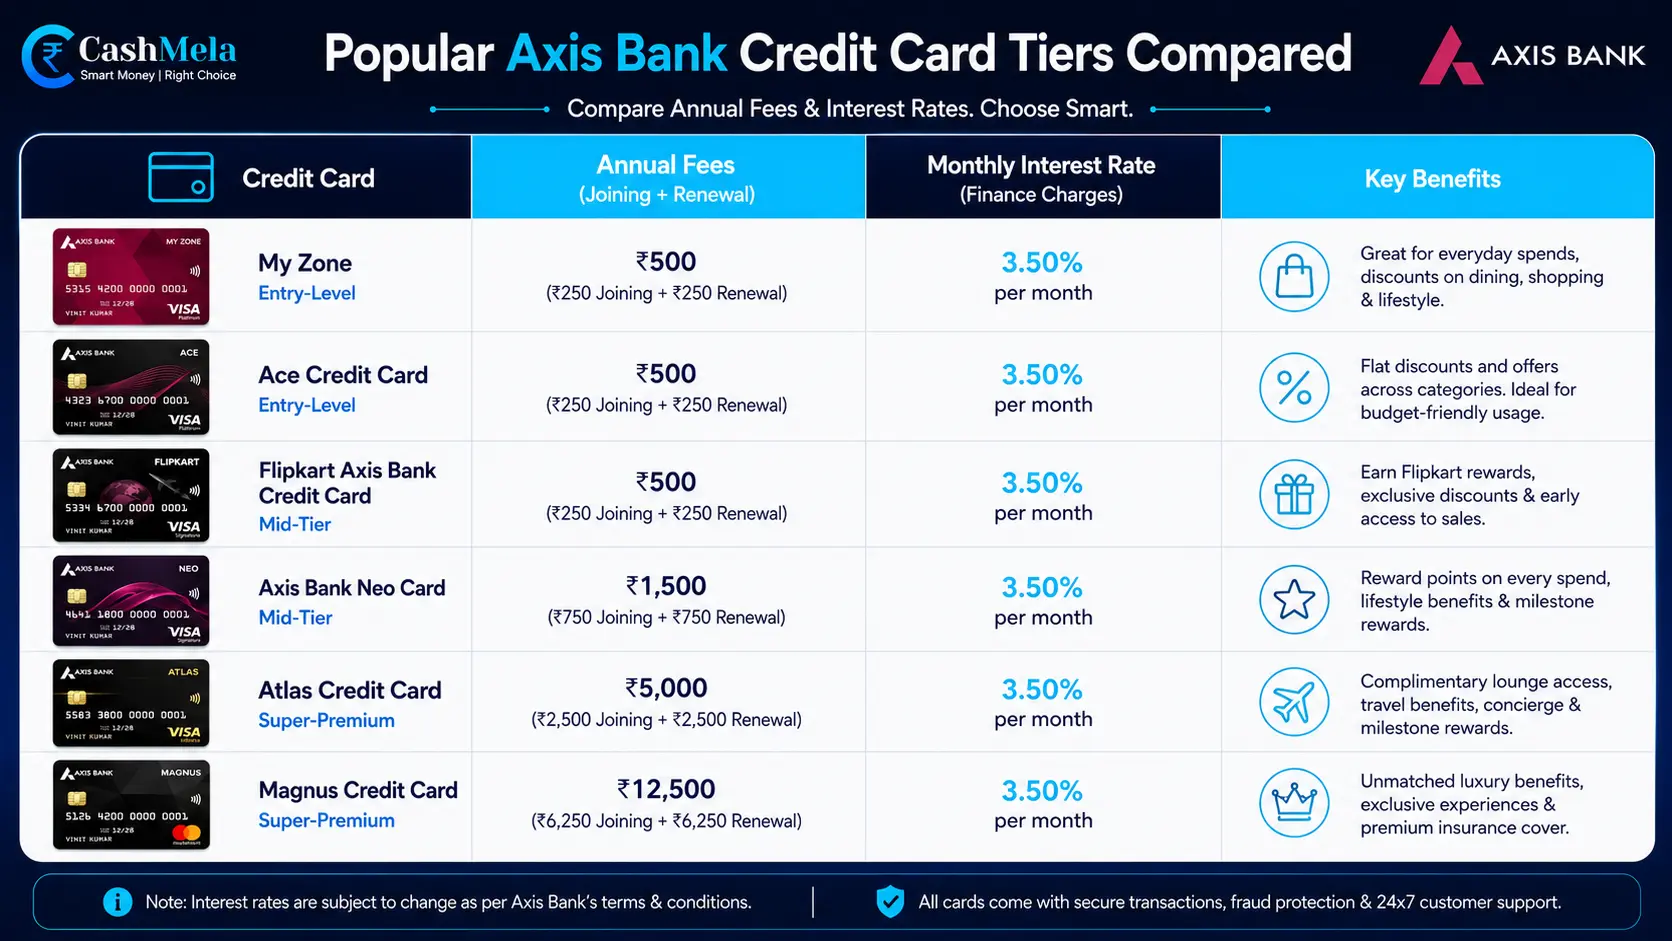
| Card Tier | Typical Annual Fee | Monthly Interest Rate |
|---|---|---|
| Neo RuPay (lifetime-free) | ₹0 | Up to 3.6%* |
| ACE (flat cashback) | ₹499, waived on spend | Up to 3.6%* |
| Flipkart / Samsung Axis | ₹500, waived on spend | Up to 3.6%* |
| Magnus (super-premium) | ₹12,500, waived on ₹25 lakh spend | 3% p.m. |
*Rates and fees vary by card and change periodically. Always confirm current figures on Axis Bank's official website before applying.
What You Need to Qualify for an Axis Bank Credit Card
Is a good income alone enough to get approved? Not quite, Axis weighs a few factors together before making a decision.
Core Eligibility Factors
- Credit score preference: A minimum credit score of 750 is generally preferred, though scores between 650 and 750 may still be considered depending on the card
- Age criteria: Age typically between 18 and 70 years, varying slightly by specific card and applicant type
- Income baseline: A minimum income threshold that rises with card tier, entry-level cards ask for considerably less than premium ones
- Existing banking relationship: An existing Axis banking relationship, which often unlocks pre-approved offers with faster processing
Understanding Axis Bank Credit Card Fees and Interest
This is the part most cardholders skim past, and it's genuinely worth slowing down for.
What You're Actually Being Charged For
- Interest-free period: Stretching up to 50 days from your statement date, applies only if you clear your full outstanding balance and haven't withdrawn cash
- Interest on carried-forward balances: Typically ranging from 1.5% to 3.75% per month depending on the specific card
- Cash advance charges: Generally 2.5% of the withdrawn amount with a minimum of ₹500, plus interest from the withdrawal date itself
- Foreign currency markup: Usually around 3.5% on international transactions, though select premium cards charge a lower 2%
A Quick Word on EMI Conversion
Worth knowing before you apply: Axis lets you convert transactions of ₹1,500 or more into EMIs across flexible tenures, six, nine, twelve, eighteen, twenty-four, or even up to forty-eight months on select cards. This comes with its own interest rate and a one-time processing fee, so it's not automatically cheaper than paying upfront, but it genuinely helps spread out larger purchases without derailing your monthly budget when used thoughtfully.
Frequently Asked Questions
Q1: Is there a genuinely fee-free Axis Bank credit card?
A: Yes, Axis offers a few lifetime-free variants like Neo RuPay, along with cards such as ACE and Flipkart Axis that waive the annual fee entirely once you cross a specific yearly spending threshold.
Q2: How long does Axis Bank credit card approval usually take?
A: Pre-approved existing customers can see near-instant approval. New applicants typically wait a few days to about two weeks depending on documentation and verification requirements.
Q3: What credit score do I need for a premium Axis Bank credit card?
A: Generally 750 or above for premium cards like Magnus, though entry-level and co-branded cards may approve applicants with a somewhat lower score.
Q4: Do Edge Reward Points expire?
A: Yes, Edge Reward Points typically expire three years from the date they were earned, so it's worth redeeming them periodically rather than letting them accumulate indefinitely.
Q5: Can I hold multiple Axis Bank credit cards at once?
A: Yes, and doing so can actually be useful, since Edge Reward Points earned across multiple Axis cards pool into a single account, making redemption more flexible.
Conclusion
Choosing the right Axis Bank credit card really comes down to matching the fee structure and rewards to how you actually spend, not to how impressive the welcome offer looks on the first page. Compare a couple of tiers honestly, check the annual fee waiver conditions before committing, and pick the card that rewards your real habits rather than an aspirational travel lifestyle you rarely live.
Ready to find your fit? Check your eligibility and apply now to compare Axis Bank credit card options built for your spending style.
Stay Informed, Stay Ahead!
Follow Cashmela on social media for more practical finance guides, loan tips, and the latest updates:
- 💰 Instagram: @cashmela_com – Simple finance tips and real borrower stories
- 👍 Facebook: Cashmela – Join the conversation and never miss an update
- 🐦 X: @cash_mela – Quick updates and finance news
- 💼 LinkedIn: Cashmela – Industry insights and company updates
✨ Let's make smarter borrowing simple, together!
Adil Patel
Founder & Chief Executive OfficerAuthor & Financial Analyst at CashMela.com
Adil Patel is the Founder of Cashmela.com. With over a decade of deep domain expertise across Indian banking, debt restructuring, and digital lending, Adil established Cashmela to liberate Indian borrowers from predatory credit card interest traps and opaque multi-EMI debt burdens. Under his leadership, Cashmela has helped over 50,000 borrowers consolidate EMIs into single, transparent, and affordable repayment plans.