Introduction
Most people only think about running a cibil credit score check the moment a loan gets rejected, and by then, it's already too late to fix anything before that particular application. The smarter move is checking regularly, the same way you'd glance at your bank balance, rather than treating it as an emergency response.
This guide walks through exactly how to do a cibil credit score check for free, which platforms are genuinely trustworthy, and what to actually do once you see your number.
Why a Regular CIBIL Credit Score Check Actually Matters
Here's a question worth asking yourself: would you rather find out about a problem three months before applying for a loan, or three minutes after getting rejected? Most people unknowingly choose the second option, simply by never checking.
What You Catch Early With Regular Checks
- Incorrectly reported late payments: Clerical mistakes or lender reporting errors that aren't actually yours.
- Sudden unexpected score drops: Often an early warning sign of identity theft or fraudulent loan inquiries.
- Creeping credit utilization: Catching card balances edging above 30% before they drag your score down.
- Post-repayment recovery: Tracking how quickly your score responds after clearing a substantial outstanding due.
Take Kavita's story as an example. A boutique owner in Surat, she assumed her credit was in good shape until a loan application got rejected out of nowhere. Running a cibil credit score check afterward revealed an old mobile phone EMI, one she'd genuinely forgotten about, still showing as overdue from two years earlier. A quick dispute resolved it, but she'd lost weeks she didn't need to lose, all because she hadn't checked sooner.
How to Do a Free CIBIL Credit Score Check, Step by Step
Is this complicated? Not even slightly, once you know where to look.
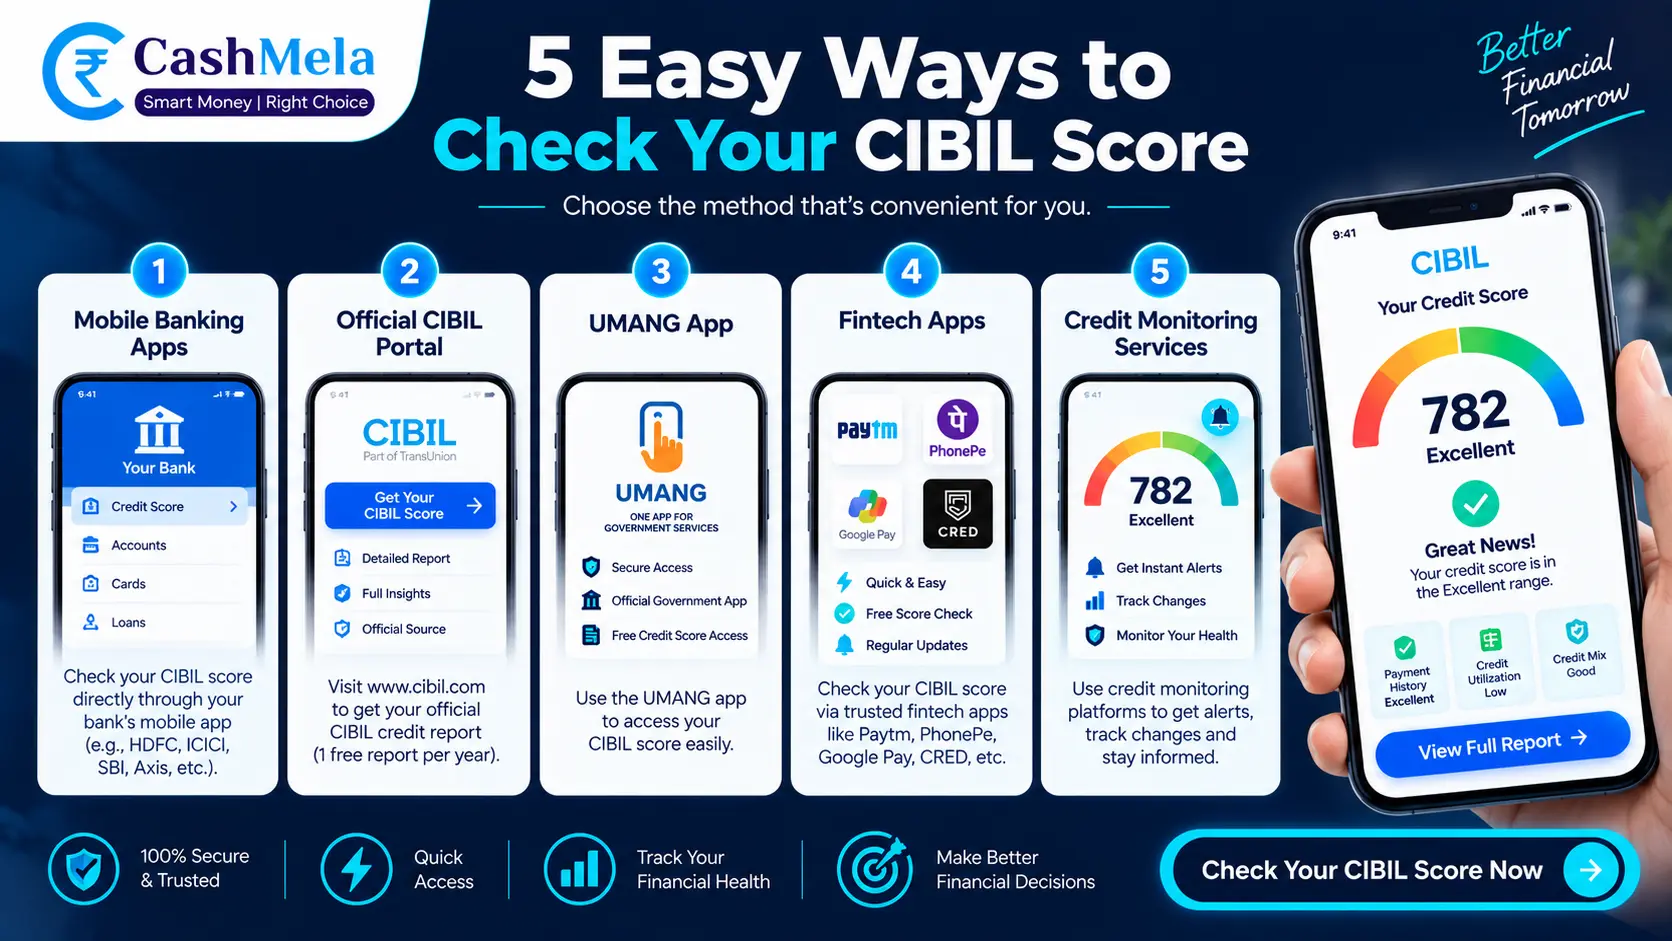
The Official Route
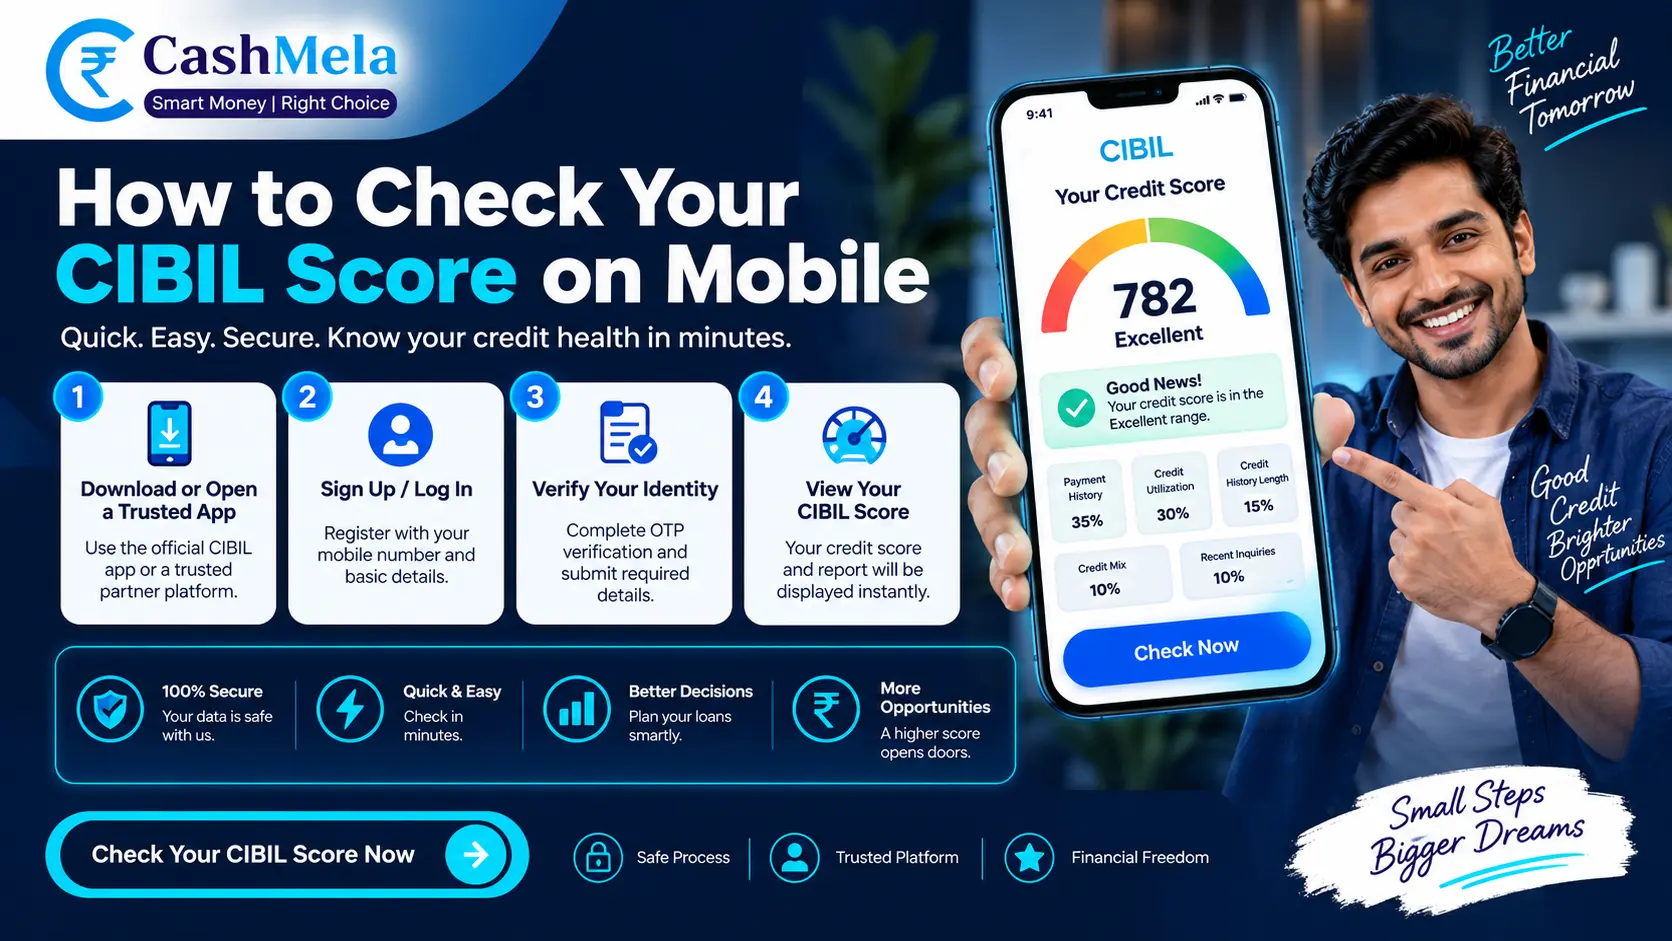
- Visit cibil.com: Navigate to the official portal and initiate registration using your PAN, full legal name, and date of birth.
- Verify your identity: Enter the OTP sent to your registered mobile number.
- Access your free credit report: Claim your full statutory credit report, available once every calendar year at no cost.
- Review your score and history: Inspect the detailed account breakdown, active loan lines, and payment track records for any inaccuracies.
The App-Based Route
Several lending platforms and financial apps also offer a free cibil credit score check, often pulling live data directly from the bureau with just your PAN and basic mobile details—no lengthy paperwork or waiting period required.
Official Site vs. Third-Party Apps
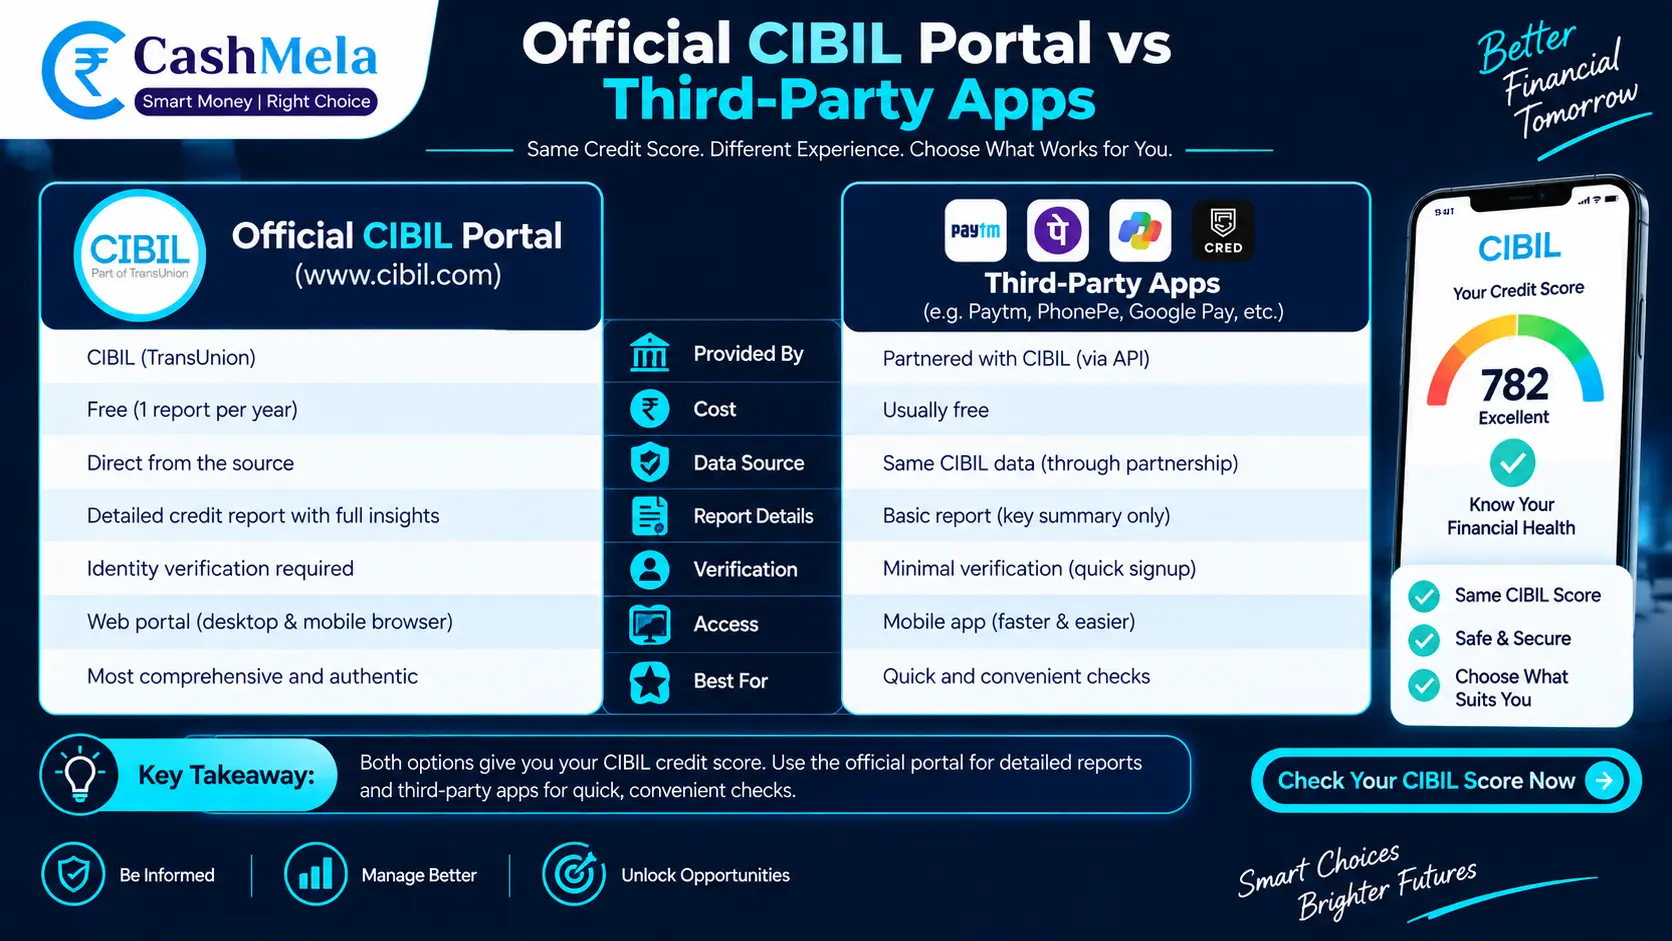
| Feature | CIBIL.com Direct | Third-Party Apps |
|---|---|---|
| Cost | Free, once per year | Often free, more frequently |
| Detail level | Full report with complete history | Usually score-only or summary |
| Setup time | A few minutes (full KYC) | Often instant (basic details) |
| Best for | Annual deep-dive review & dispute filing | Quick, regular monthly monitoring |
What to Do Right After Your CIBIL Credit Score Check
Getting the number is only step one, what you do with it matters just as much.
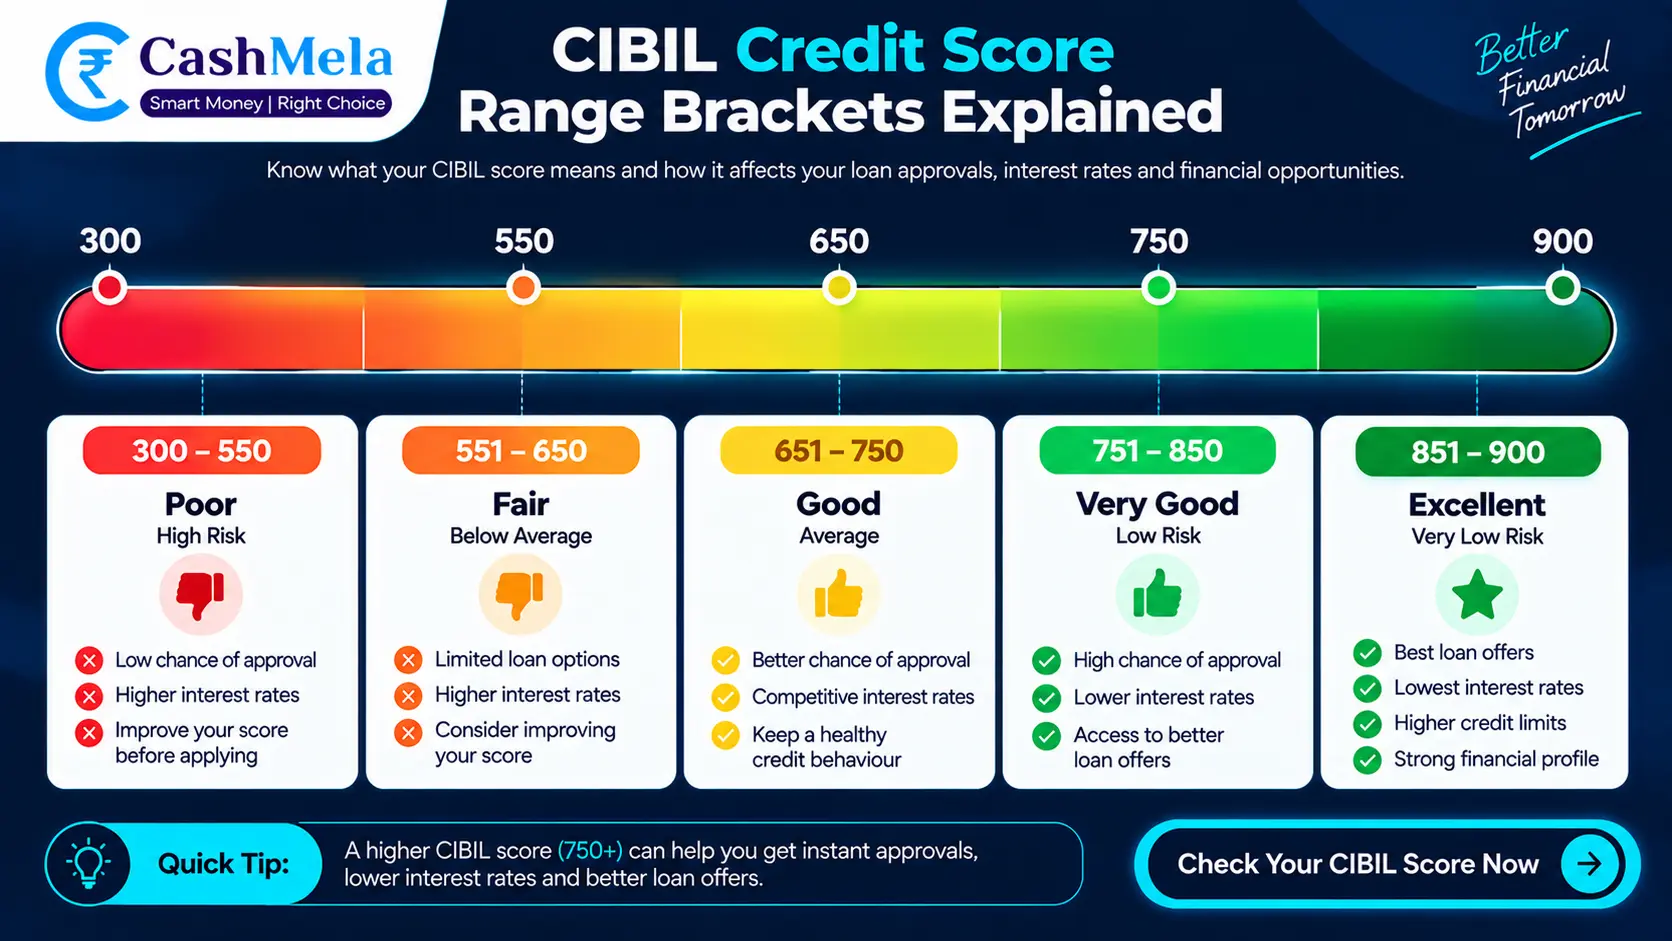
If Your Score Looks Good (750+)
- Log your score and monitor quarterly: Note down your score and check again in three to six months. Avoid checking daily—scores don't move that fast.
- Negotiate better borrowing terms: Consider applying for lower interest rates or higher limits on existing loans if your score has improved significantly since you first borrowed.
If Your Score Is Lower Than Expected
- Examine the full report line by line: Read through every account entry, not just the overall number. Reporting errors are far more common than people assume.
- Dispute inaccuracies promptly: File a formal dispute directly through the bureau's official grievance redressal portal.
- Focus on the two main levers: Prioritize 100% on-time payments and reducing credit card utilization below 30% before worrying about other secondary factors.
A Habit Worth Building Around Your CIBIL Credit Score Check
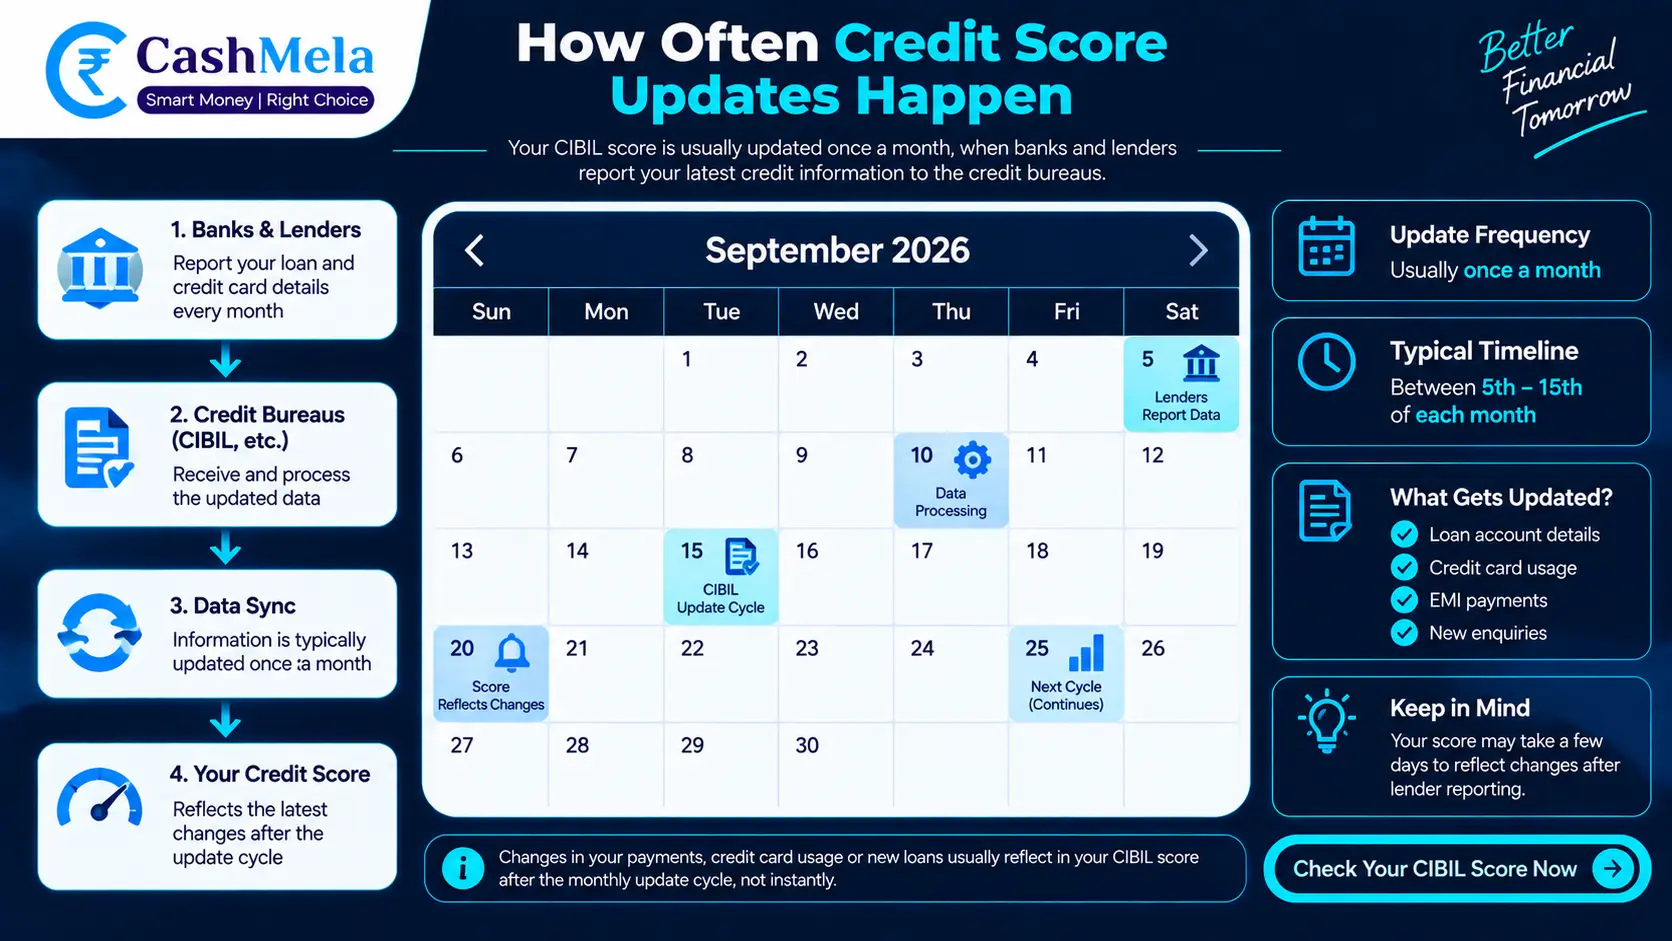
Treat this less like a one-off task and more like a recurring calendar reminder, the same way you'd schedule a routine health checkup. Pick a fixed date every few months, perhaps the first weekend of each quarter, and make your cibil credit score check part of that same routine.
Consistency here matters more than any single check ever will, since it's the trend over time, not one snapshot, that actually tells you whether your financial habits are working.
Frequently Asked Questions
Q1: Does running a cibil credit score check lower my score?
A: No, checking your own score counts as a soft inquiry and has zero effect on the number. Only a lender's hard inquiry, triggered when you actually apply for credit, can cause a small, temporary dip.
Q2: How often should I actually check my score?
A: Every three to six months is a reasonable rhythm for most people, more frequently if you're actively planning to apply for a loan or credit card soon.
Q3: Is a free cibil credit score check through an app as accurate as the official site?
A: Generally yes, if the app is a genuine RBI-approved partner pulling live bureau data. Always verify the app's credibility before entering sensitive details like your PAN.
Q4: What should I do if I find an error during my check?
A: Raise a dispute directly through CIBIL's online grievance portal, attaching any supporting documents. Resolution typically takes a few weeks depending on the complexity of the correction.
Q5: Can I check my score if I've never taken a loan or credit card before?
A: No, a CIBIL score only exists once you've had an active loan or credit card reported within the past 36 months. Without credit history, your report shows "NA" instead of a number.
Conclusion
Making a cibil credit score check a regular habit, rather than a panic response after rejection, genuinely puts you in control of your borrowing future. Use the free official route once a year for a full report, lean on a trusted app for quicker regular check-ins, and act promptly on anything that looks off. A few minutes now can save you weeks of frustration later.
Ready to see what you qualify for? Check your eligibility and apply now for a loan or card that matches your credit profile.
Stay Informed, Stay Ahead!
Follow Cashmela on social media for more practical finance guides, loan tips, and the latest updates:
- 💰 Instagram: @cashmela_com – Simple finance tips and real borrower stories
- 👍 Facebook: Cashmela – Join the conversation and never miss an update
- 🐦 X: @cash_mela – Quick updates and finance news
- 💼 LinkedIn: Cashmela – Industry insights and company updates
✨ Let's make smarter borrowing simple, together!
Adil Patel
Founder & Chief Executive OfficerAuthor & Financial Analyst at CashMela.com
Adil Patel is the Founder of Cashmela.com. With over a decade of deep domain expertise across Indian banking, debt restructuring, and digital lending, Adil established Cashmela to liberate Indian borrowers from predatory credit card interest traps and opaque multi-EMI debt burdens. Under his leadership, Cashmela has helped over 50,000 borrowers consolidate EMIs into single, transparent, and affordable repayment plans.