Introduction
If you've scanned a shop's UPI QR code with your credit card instead of your debit card recently, you were almost certainly using a RuPay credit card. That's not a coincidence, it's the one genuine advantage this network holds over Visa and Mastercard in India, the ability to pay through UPI directly from your credit limit rather than your bank balance.
This guide breaks down what actually makes the network different, the real benefits worth knowing about, and how to pick a card that fits your everyday spending without getting distracted by marketing fluff.
What Makes a RuPay Credit Card Genuinely Different
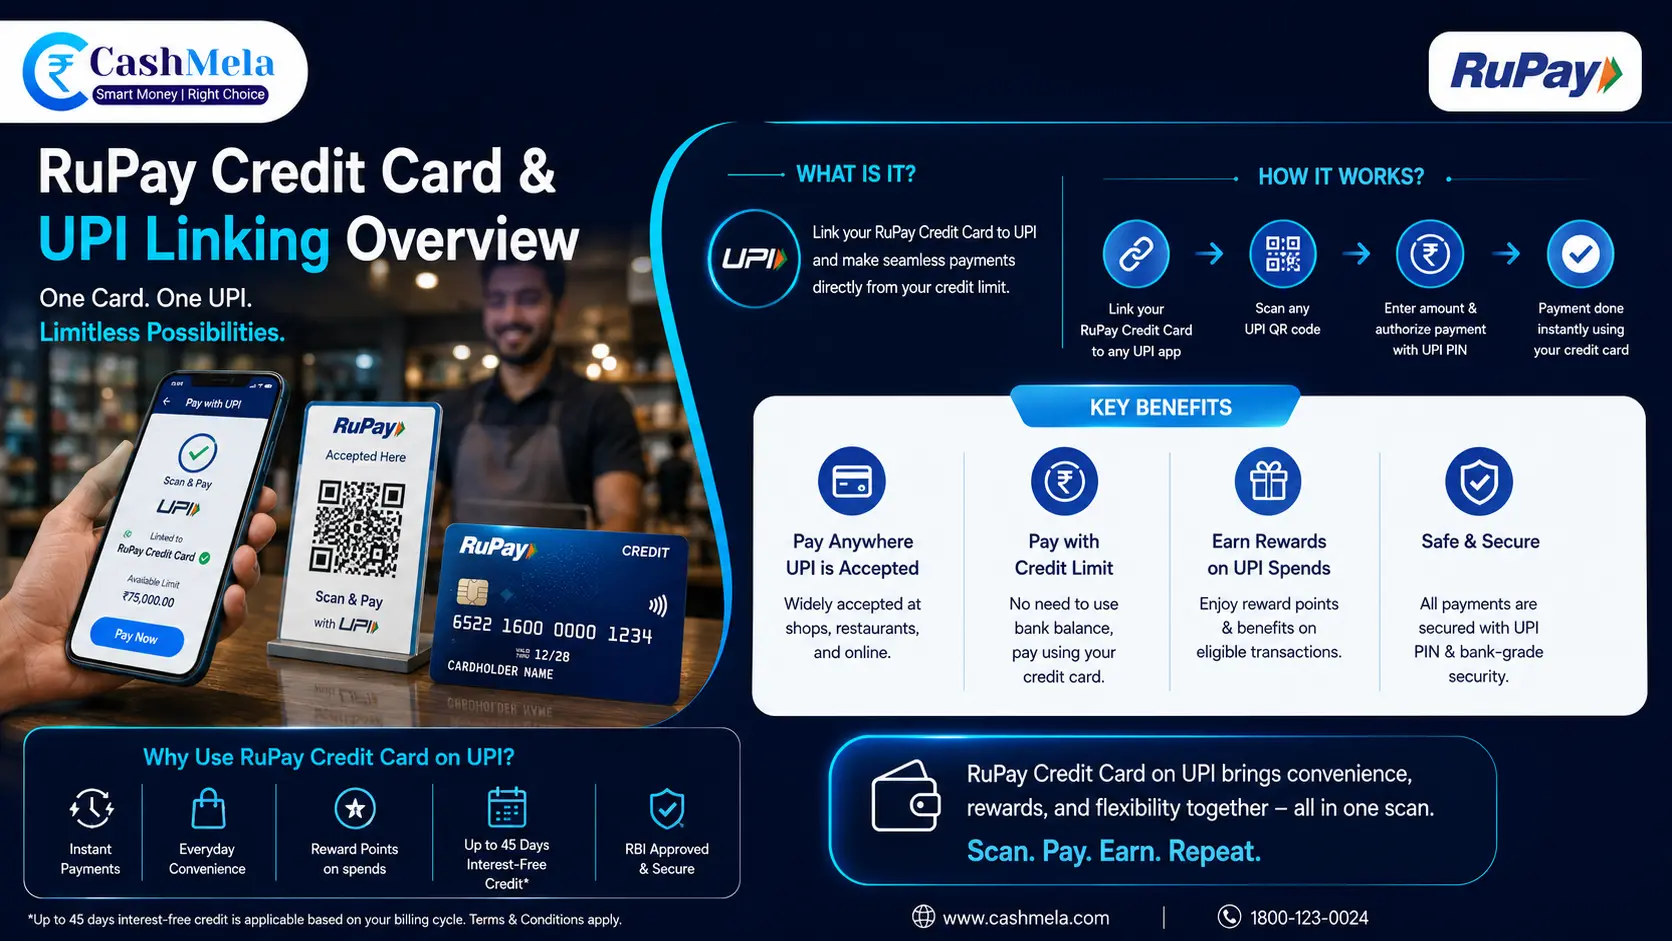
Here's a question worth asking: why would India's own payment network matter when Visa and Mastercard already work everywhere? The answer comes down to one feature neither of them offers, native UPI integration.
The Core Advantage Explained
- Direct UPI linking: Letting you pay at any QR code using your credit limit instead of your savings account balance
- No extra charges on most UPI transactions: Since issuers typically don't pass on any fee to the cardholder for everyday payments
- Works through apps you already use: Including PhonePe, Google Pay, Paytm, CRED, and BHIM
- Built on India's own payment rails: Run by NPCI rather than an international card network
Take Deepak's story as an example. A small grocery shop customer in Nagpur, he used to pay every UPI transaction straight from his savings account, missing out on rewards entirely. After linking his RuPay credit card to his UPI app, the same monthly grocery run that once earned him nothing now quietly builds reward points, while his actual cash sits untouched in his account until the bill comes due.
RuPay vs. Visa and Mastercard for Everyday Use
When deciding whether to add a RuPay credit card to your wallet, it helps to understand how it stacks up against traditional Visa and Mastercard networks across key everyday banking criteria:
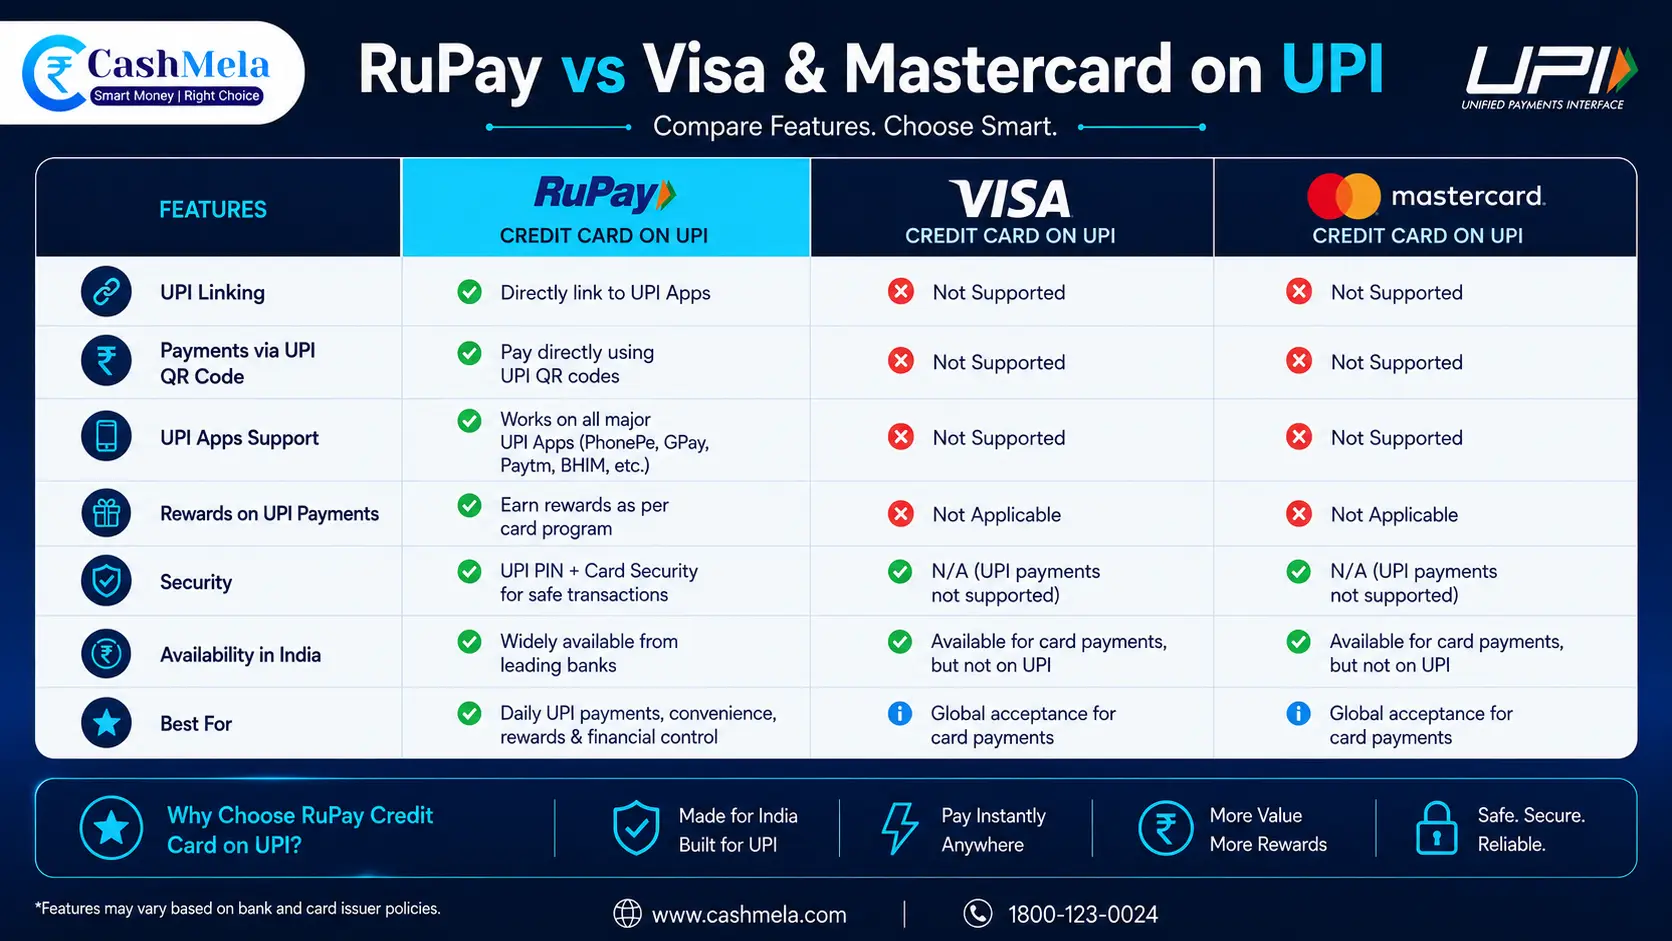
| Feature | RuPay Credit Card | Visa / Mastercard Credit Card |
|---|---|---|
| UPI QR payments | Yes, direct from credit limit | Not supported |
| Global acceptance | Growing, still narrower than Visa/Mastercard | Wider international acceptance |
| Rewards on UPI spends | Yes, on eligible transactions | Not applicable |
| Typical annual fee | Often lower or lifetime-free variants | Varies widely by card |
How to Actually Link Your RuPay Credit Card to UPI
Is this complicated to set up? Genuinely not, the whole process takes a few minutes on most apps.
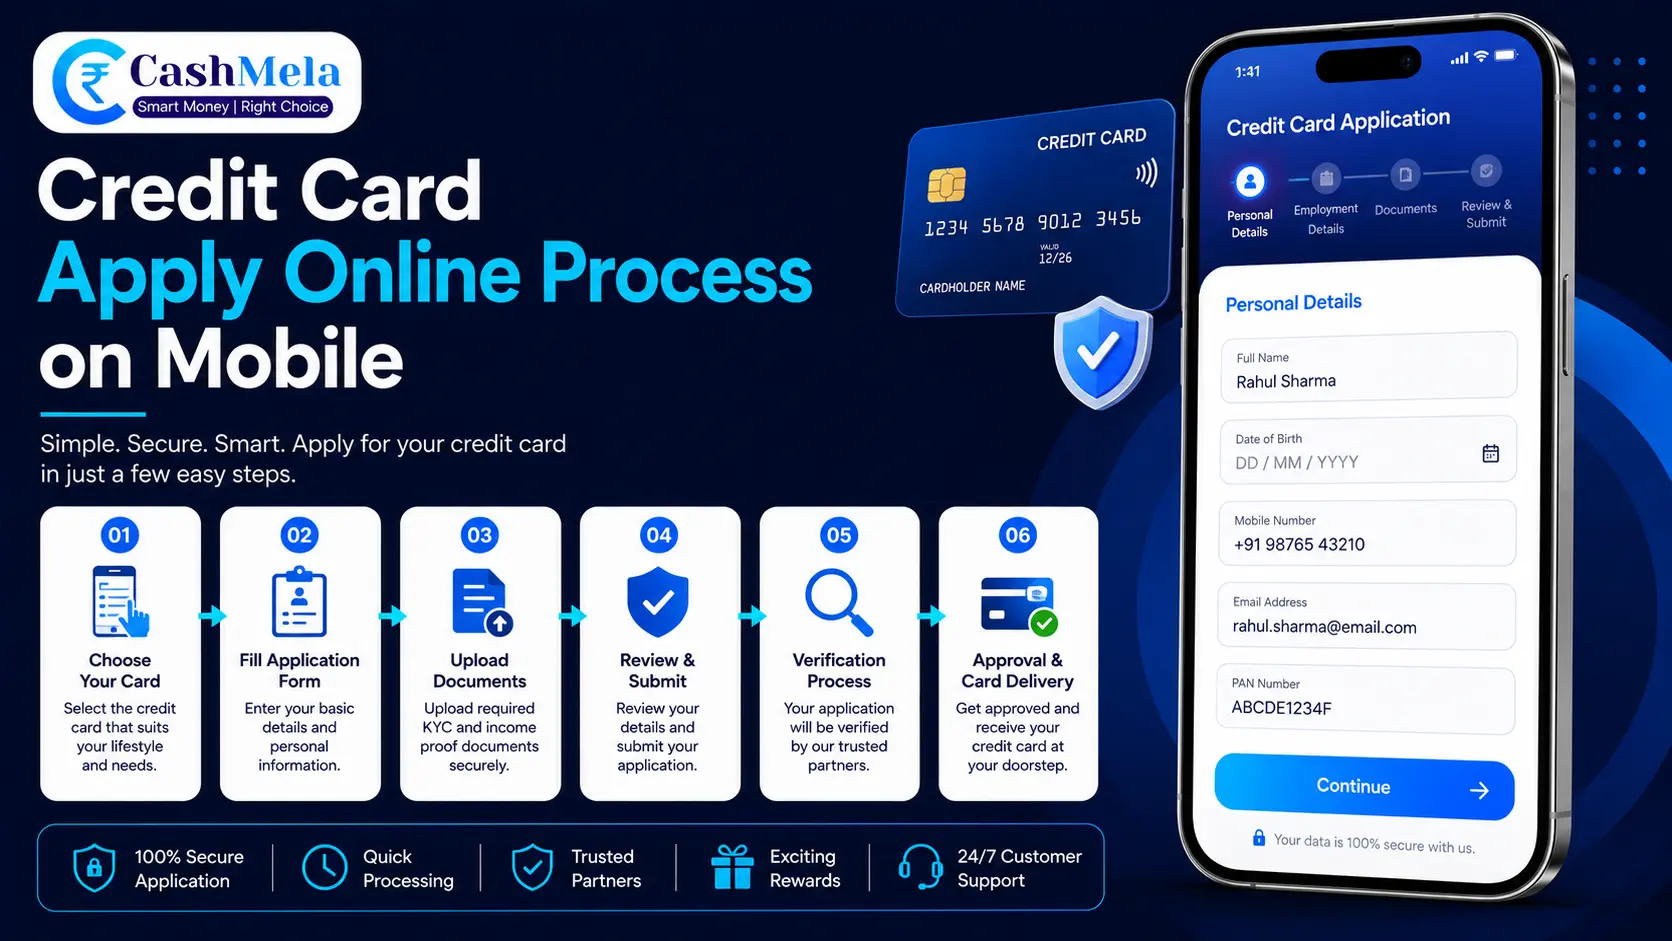
Step-by-Step Linking Process
- Open your preferred UPI app: PhonePe, Google Pay, Paytm, or BHIM
- Select "Add Credit Card": Or a similar option under payment methods
- Choose RuPay as the network: And enter your card details
- Set a dedicated UPI PIN: For credit card transactions, separate from your regular UPI PIN
- Start paying at any UPI QR code: Using your pre-approved credit line
Troubleshooting Tip: If linking fails, the most common causes are an outdated app version or a card not yet enabled for UPI by your issuing bank. Updating the app or contacting your card issuer usually resolves it.
A Quick Note on Fees and Card Variants
Not every RuPay credit card charges the same fees, and this genuinely surprises a lot of first-time applicants. Several entry-level and co-branded variants come as lifetime-free, with zero annual charge, while premium options carry a joining and renewal fee similar to any other card network.
Before choosing one, it's worth checking whether the specific card offers UPI linking at all, since a handful of older or basic variants still don't support it, even though most current issuances do.
Who Should Genuinely Consider a RuPay Credit Card
Good Fits for This Card Type
- Everyday UPI Spenders: Anyone who already pays frequently via UPI and wants to start earning rewards on those transactions
- First-time Credit Card Users: Looking for lifetime-free or low-fee entry options
- Small Business Owners & Shopkeepers: Who receive UPI payments and want a domestic, cost-effective card
- Supporters of Domestic Infrastructure: Users who value keeping their spending on India's own payment infrastructure rather than international networks
It's worth being honest about who this isn't ideal for too. If most of your spending happens on international websites or during frequent overseas travel, a Visa or Mastercard product will likely serve you better as your primary card, with this one as a useful secondary option for domestic UPI spending specifically.
Frequently Asked Questions
Q1: Does using a RuPay credit card on UPI cost extra?
A: No, for the vast majority of everyday transactions, cardholders don't pay any additional fee. Merchants may bear a small fee set by NPCI, but this typically isn't passed on to you.
Q2: Can a RuPay credit card improve my credit score?
A: Yes, RuPay cards report to credit bureaus the same way Visa and Mastercard cards do, so timely repayment and low utilization on a RuPay card build your credit history just as effectively.
Q3: Which UPI apps support RuPay credit card linking?
A: Most major apps support it, including PhonePe, Google Pay, Paytm, CRED, and BHIM. It's worth updating your app to the latest version if the linking option doesn't appear.
Q4: Is a RuPay credit card accepted internationally?
A: Acceptance has grown but still remains narrower than Visa or Mastercard for international transactions, so if you travel abroad frequently, it's worth carrying a secondary card too.
Q5: Are there premium RuPay credit card options with lounge access?
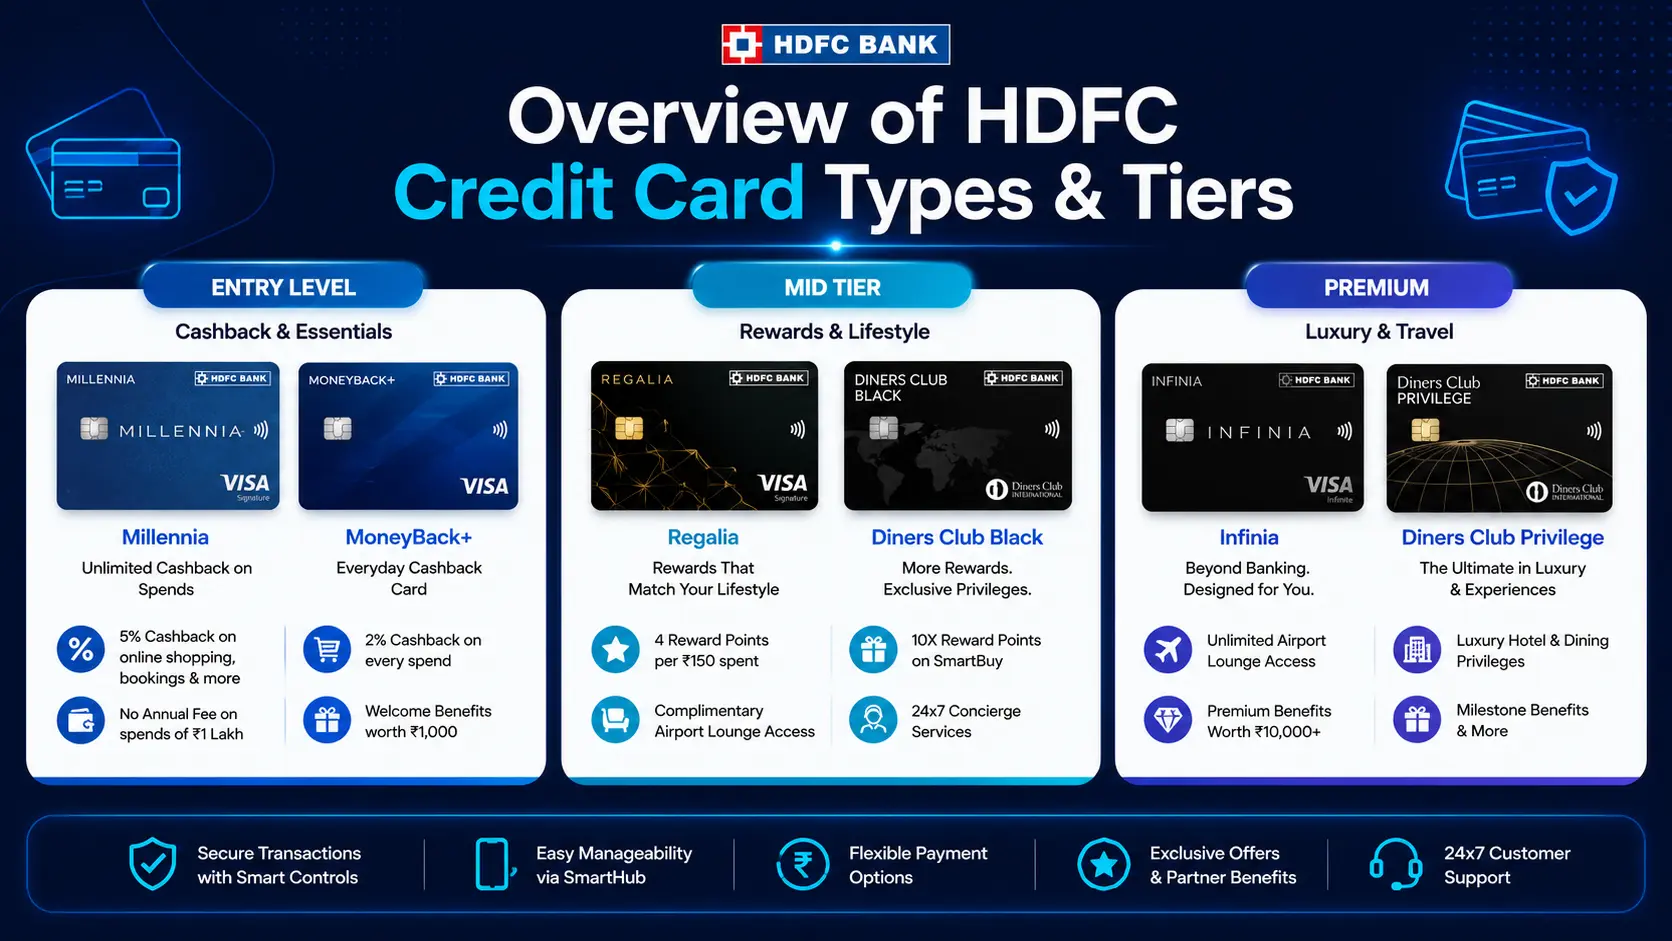
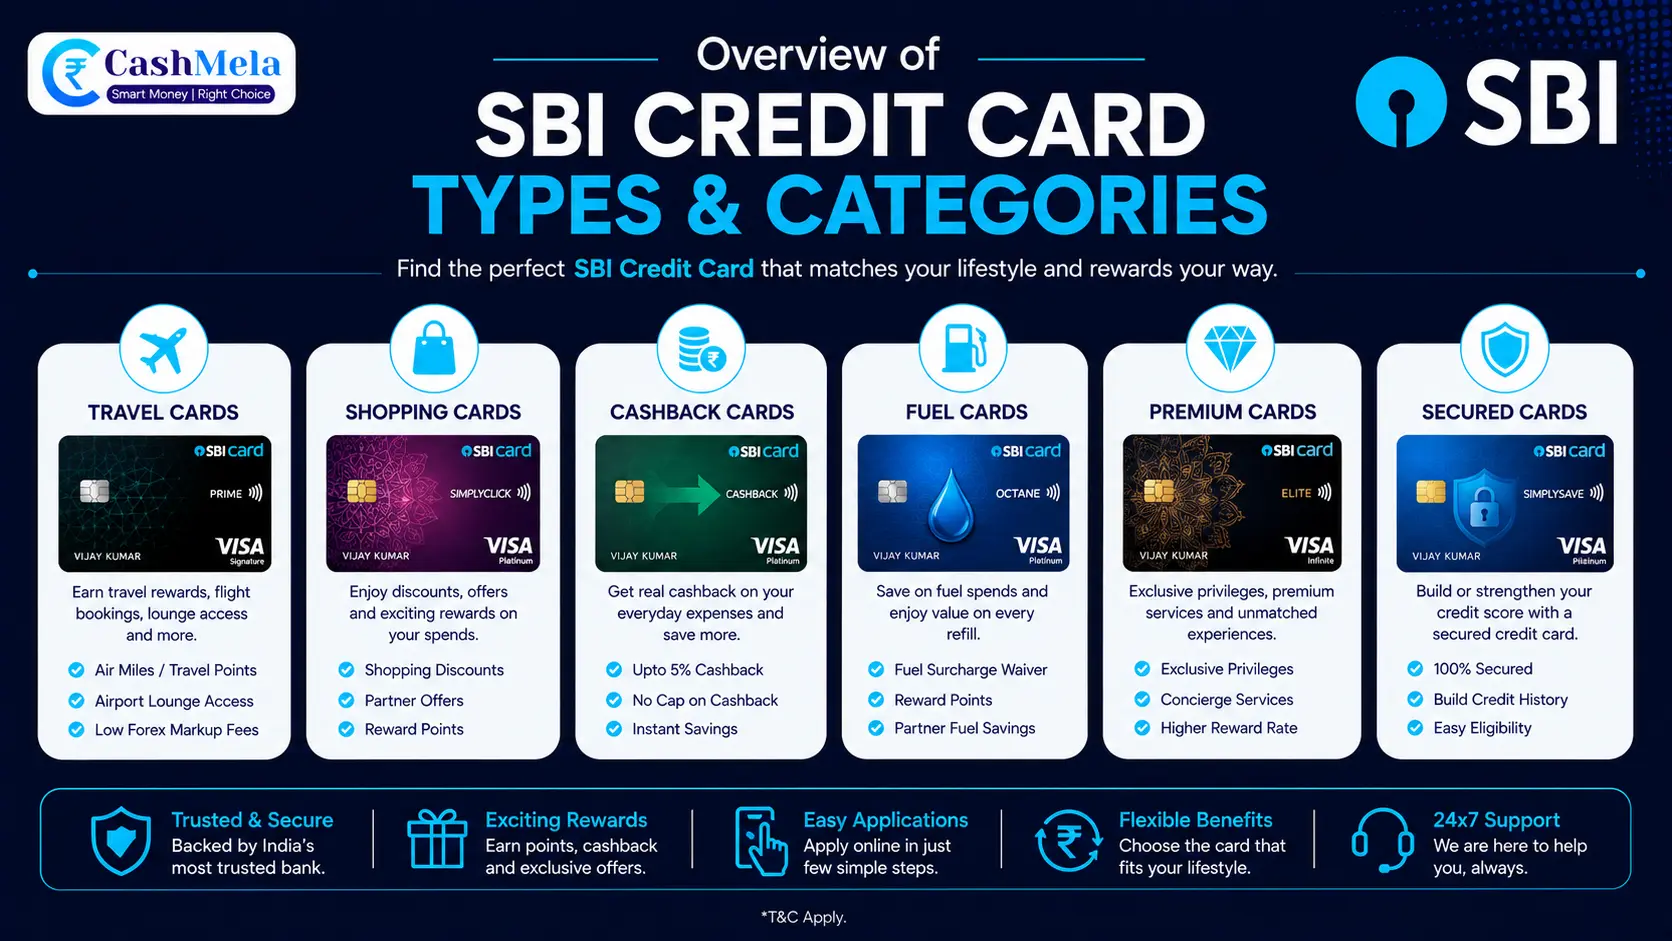
A: Yes, several banks including HDFC, SBI, Axis, and ICICI offer premium RuPay variants with airport lounge access and travel benefits, alongside the entry-level and lifetime-free options.
Conclusion
A RuPay credit card genuinely earns its place in your wallet if you're already a heavy UPI user, since it turns everyday QR payments into a rewards-earning habit rather than money simply leaving your account unnoticed. Compare a couple of card variants, check the UPI linking process with your preferred app, and pick one that matches how you actually pay day to day, rather than chasing whichever card your friend happens to recommend.
Ready to get started? Check your eligibility and apply now to find a RuPay credit card that fits your spending style.
Stay Informed, Stay Ahead!
Follow Cashmela on social media for more practical finance guides, loan tips, and the latest updates:
- 💰 Instagram: @cashmela_com – Simple finance tips and real borrower stories
- 👍 Facebook: Cashmela – Join the conversation and never miss an update
- 🐦 X: @cash_mela – Quick updates and finance news
- 💼 LinkedIn: Cashmela – Industry insights and company updates
✨ Let's make smarter borrowing simple, together!
Adil Patel
Founder & Chief Executive OfficerAuthor & Financial Analyst at CashMela.com
Adil Patel is the Founder of Cashmela.com. With over a decade of deep domain expertise across Indian banking, debt restructuring, and digital lending, Adil established Cashmela to liberate Indian borrowers from predatory credit card interest traps and opaque multi-EMI debt burdens. Under his leadership, Cashmela has helped over 50,000 borrowers consolidate EMIs into single, transparent, and affordable repayment plans.